
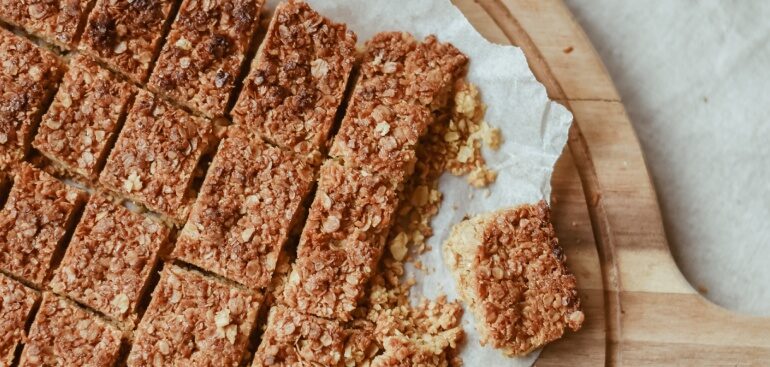
The distinction between zero-rated food and standard VAT confectionery is a crucial, and complex, one – not helped by what may appear to be apparently arbitrary rulings. Despite its predecessor losing a notorious ruling over the zero-rating of Jaffa Cakes more than 30 years ago, HMRC refuses to give ground on marginal cases. The latest target was the simple flapjack.
As an example of the complexity, tap water is
zero-rated, but a bottle of water is not (although a bottle of milk is). It
‘logically’ follows that ice is zero-rated if made from tap water, but not if
from bottled water – although good luck telling the difference. Baked goods are
a similar minefield.
Flapjacks
There might be little obvious difference
between a flapjack and a cereal bar, but flapjacks benefit from zero-rating,
being classed as cakes, simply because they were around first. The more recent
cereal bars are classed as VAT-able confectionery.
Not surprisingly, HMRC is not at all happy
with the distinction, and define flapjacks as narrowly as possible.
·
HMRC only allow zero-rating of
‘standard’ flapjacks, along with minor variations, such as the addition of dried
fruit or chocolate chips.
·
HMRC will not accept any
alteration to a flapjack that takes it into the category of being a cereal bar.
In two cases, HMRC pursued these distinctions to the
detriment of the companies involved.
Glanbia Milk
This company was recently on the wrong side
of a First-Tier Tribunal decision. Compared to a ‘standard’ flapjack purchased
in a cafe or at a supermarket, the flapjacks produced by Glanbia Milk had fewer
calories, about 10 times less sugar, and very low levels of fat. The products
were not baked like traditional flapjacks, and contained significant amounts of
protein, an ingredient not traditionally associated with cakes.
DuelFuel
This small start-up has hit a similar problem
with its range of flapjacks and protein cake bars, and may have to close as a
result. HMRC is not permitting zero-rating for their products because of issues
similar to the Glanbia Milk case. Based on the taste, texture, ingredients,
packaging and marketing, the products produced by DuelFuel are not considered
to be cakes.
If you are tempted to embark on a baking
career, be warned. HMRC guidance on the VAT treatment of food products (VAT
Notice 701/14) can be found here.