A timely warning for company tax returns

tax

The deadline for filing a company’s corporation tax return with HMRC is 12 months after the end of the accounting period it covers. HMRC warns that it will charge a penalty if a return is not filed on time.

Online filing

Corporation tax returns can now only be filed online using commercial software, with HMRC having closed its free online corporation tax filing service on 31 March 2026:

  • Any changes or amendments to previously submitted tax returns also have to be made using commercial software.
  • HMRC no longer accepts amendments by letter.

HMRC publishes a list of commercial software suppliers for corporation tax. It makes sense to use software that will also file annual accounts with Companies House.

Paying corporation tax

Despite the 12-month tax return filing deadline, corporation tax usually needs to be paid nine months and one day after the end of the accounting period.

If it is not possible to file the return by this earlier deadline, an estimated payment can be made to minimise the amount of late payment interest which will be charged. The rate is currently set at 7.75%.

For a company with a 31 March 2026 year-end, the tax return is due by 31 March 2027. However, corporation tax will normally need to be paid by 1 January 2027, if late payment interest is to be avoided.

Loss relief claims

Should a corporation tax return involve the carry back of losses to a previous accounting period, HMRC has clarified that the correct treatment is to tick box 45 on the return to indicate that a repayment for an earlier accounting period is due.

A breakdown of the claim must then be included to show how losses have been used. There is no need to amend the return for the earlier accounting period.

HMRC’s list of commercial software suppliers for corporation tax can be found here.
No deadline extension for weekends or bank holidays

Deadline

HMRC are having to remind taxpayers that there is no deadline extension if a VAT return submission date falls on a weekend or a bank holiday.

Due date reminder

The due date for submitting quarterly VAT returns is one month plus seven days after the end of the quarter. So, for the quarter ending 30 June, that’s 7 August:

  • It is the same deadline for paying HMRC, although you need to allow time for a payment to clear HMRC’s account.
  • If you use the annual accounting scheme, the VAT return is normally due two months after the end of the accounting period.

HMRC has responded to a growing trend of late VAT return submissions and VAT payments based on incorrect information provided by artificial intelligence (AI) and third-party websites. VAT returns can be submitted over the weekend or on a bank holiday, and, if this is not possible, a return should be submitted on the last working day prior to the due date.

Penalty warning

Despite HMRC’s warning, taxpayers who are occasionally late should avoid any penalty except for late payment interest:

  • Late payment penalty: HMRC only charges a penalty if a VAT payment is made more than 15 days late, so this will not be an issue if a taxpayer simply waits until the first working day after the payment deadline.
  • Late submission penalty: Being a day late will mean a penalty point is incurred, but there is no £200 penalty until a threshold of four points is reached (two points if submitted annually), and points expire after 24 months, provided the taxpayer remains below the threshold.
  • Late payment interest: This is charged – currently at a rate of 7.75% – from the due date to the date of payment. For instance, being ten days late on a VAT payment of £40,000 will see interest of just under £85 being charged.

Submitting one late quarterly VAT return each year should not lead to a late submission penalty being charged.

HMRC guidance on penalty points and penalties if you submit your VAT Return late can be found here.

What goes into the tax cocktail?

tax cocktail

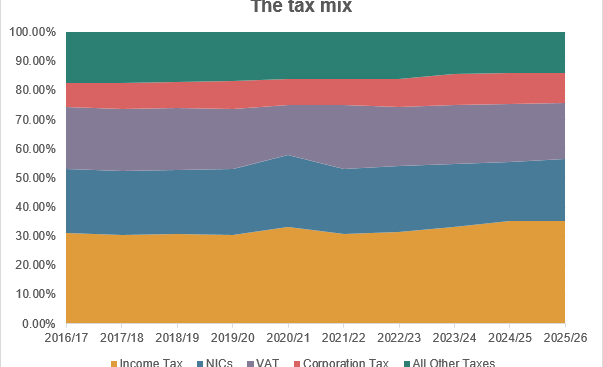
New data from HMRC shows how much the government relies on just four taxes.

Source: HMRC

The Labour Party went into the 2024 general election with pledges on four major taxes in its manifesto:

  • “Labour will not increase taxes on working people, which is why we will not increase National Insurance, the basic, higher, or additional rates of Income Tax, or VAT.”
  • “Labour will cap corporation tax at the current level of 25 per cent, the lowest in the G7, for the entire parliament…”

At the time, the tax promises were seen as politically necessary to counter suggestions that a Keir Starmer government would operate tax-and-spend policies. However, the quadruple tax lock was widely criticised by many economists for the half decade constraint that it placed on the Chancellor in uncertain times.

Fast forward about two years from the publication of that manifesto, and the economists have been vindicated. New data from HMRC, published at the end of April, showed that in the past tax year, income tax, national insurance (NI), VAT and corporation tax accounted for 86% of all tax receipts. That is not surprising – as the graph shows, over the past ten years, the quartet account for more than £4 out of every £5 tax collected.

Despite the manifesto promise, income tax receipts rose by 9% in 2025/26 from the previous year – faster than the growth in prices or the UK economy. That outpacing is due to the freezing of the personal allowance and tax thresholds, dragging more people into tax and more existing taxpayers into higher tax bands.

NI receipts grew even faster – 16.3% up – thanks to the manifesto-challenging changes to the level of employer’s NI contributions. Together, NI and income tax – the two taxes on earnings – accounted for 56.5% of all that flowed into HMRC’s coffers.

The jumps in taxes on earnings contrasted with the growth in the third largest source of tax, VAT, which grew by 5.7%. Corporation tax had even slower growth (4.6%), but that might be because employers claimed more tax relief on those higher NI contributions.

The dominance of the big four manifesto-locked taxes explains why the Chancellor has made so many tweaks to the overall system to raise additional revenue. Be prepared: it is beginning to look like that process will be repeated at the next Budget.

For HMRC’s latest bulletin on tax receipts and NI contributions, visit here.